
Investors
Investor resources
Fiscal information for US investors
Trust 1622 has elected to be treated as a corporation for US federal income tax purposes. Consequently, for US federal income tax purposes, dispositions and transfers of interests in Trust 1622 should be subject to the treatment applicable to the disposition or transfer of corporate stock. US tax rules specific to the treatment of the disposition or transfer of interests in a partnership—including Section 1446(f) of the US Internal Revenue Code—should not apply in respect of Trust 1622.
It is also our view that Trust 1622 should not be considered a passive foreign investment company (“PFIC”) given that a foreign company would be considered a PFIC only if (i) at least 75% of its gross income is passive income or (ii) at least 50% of the value (determined based on a quarterly average) of its assets is attributable to assets that produce passive income or which are held for the production of passive income. Passive income includes rents, however, rents from real property generally will not be treated as passive income (and real property producing these rents generally will not be treated as passive assets) if they are derived from leasing real property with respect to which the lessor, through its own officers or employees, regularly performs active and substantial management and operational functions while the property is leased.
For FY 2012 and 2013 we believe that FMQ was a PFIC for U.S. federal income tax purposes given the management and operation of FMQ’s properties were performed by third parties. In 2014, however, FMQ established an internal property administration platform (“MPA”), which provides leasing, accounting, operational and other property administration services with respect to FMQ’s industrial properties. MPA, through its officers and employees, provides a number of management and operational functions with respect to FMQ’s properties. We consider that these activities should constitute active and substantial management and operational functions for purposes of the PFIC rules. Furthermore, FMQ has elected to treat MPA as a “disregarded entity”, which is wholly owned by FMQ, for United States federal income tax purposes. Therefore, FMQ will be treated, for purposes of the PFIC rules, as performing any activities undertaken by MPA. As such, since 2014 we believe the rents received from the properties managed by MPA should not be treated as passive income and such properties should not be treated as passive assets for purposes of the PFIC rules.
Quick Links
Contact us
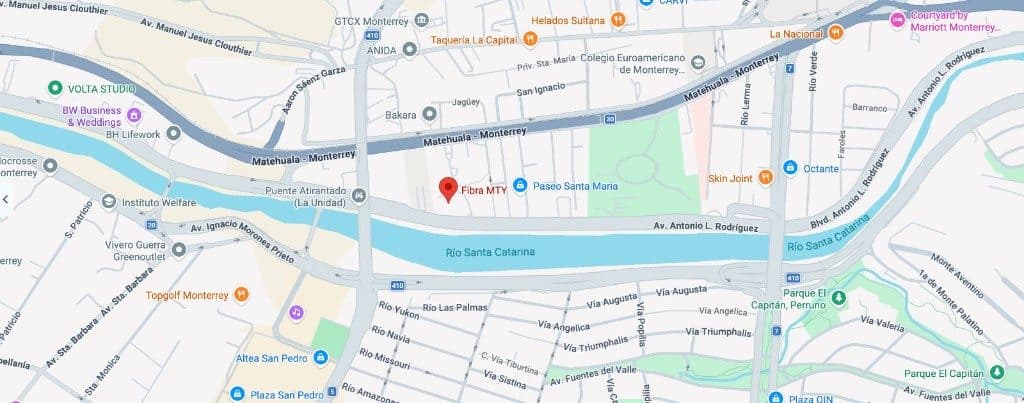 Get directions
Our corporate office
Oficinas en el Parque, Blvd. Antonio L. Rodríguez 1884-Torre 1,
Santa María, 64650 Monterrey, N.L., Mexico.
it@fibramty.com
+52 (55) 9178 7700